Condo Master Policy Deductible in Virginia: Questions to Ask After a Leak

BYSteve Jafari, General ManagerNORTHERN VIRGINIA, MARYLAND & D.C.
After a leak in a Virginia condominium, the answers about who is responsible for what are in your association's recorded declaration, its master policy and your own unit owner policy. Coverage depends on your policy and your insurer's decision. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney. This guide explains the terms associations use, the documents to request from management, and what we document on a stacked-housing water loss. We invoice the property owner and do not represent you in your claim.
Call 1-888-29-FLOODWhich documents define responsibility when water crosses a unit boundary?
In a condominium, the association's recorded declaration, its bylaws and the master policy form it bought are the documents that describe what the association maintains and what each owner maintains. Your own unit owner policy, often called an HO-6, is a separate document.
Coverage depends on your policy and your insurer's decision. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney.
What do all-in and bare-walls mean?
Associations and insurance professionals use the terms all-in (sometimes written all-inclusive) and bare-walls to describe how a master policy is written, and single entity for a form between the two. The terms refer to how far the master policy reaches into the interior of a unit. Every association wrote its own declaration, so two buildings a few miles apart can differ.
Which term describes your building is a question for your association's management, and what that means for a particular loss is a question for your insurer or agent.
How do you find out which one your building has?
Ask the management company for two things in writing: the current master policy declarations page, and the insurance article of the recorded declaration. The declarations page names the carrier and the deductible. The insurance article describes where the association's duty to repair stops and yours begins.
A certificate of insurance is not a substitute for the declarations page, so ask for the declarations page by name. If you bought recently, the resale documents you received before closing probably include both, so check the closing file first. If you have owned the unit for years, request a fresh set, because boards change carriers at renewal and members amend bylaws.
- The master policy declarations page, showing the carrier and the per-occurrence deductible
- The insurance article of the recorded declaration, plus any amendments
- Any board resolution about charging a deductible back to a unit owner
- Your own HO-6 declarations page, so you can compare the documents side by side
What is an HO-6 policy?
An HO-6 is the name for a unit owner policy. What your HO-6 includes, and in what amounts, is stated in your own policy and declarations page.
Ask your agent to walk you through it. Coverage depends on your policy and your insurer's decision. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney.
Who pays the master policy deductible?
The association's governing documents and any board resolution adopted under them describe how the association handles its master policy deductible. We do not interpret those documents. Where they are ambiguous, the question belongs with a lawyer who reads Virginia community association law.
Ask management for the declaration, the bylaws and any resolution. Coverage depends on your policy and your insurer's decision. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney.
What is loss assessment?
Loss assessment is the term for a charge an association passes to its owners, and an endorsement of that name is something a unit owner policy may include. Ask your agent whether your policy has one and read its wording.
Questions about it belong with your insurer or agent.
What is different about a sewer or drain backup in a condo?
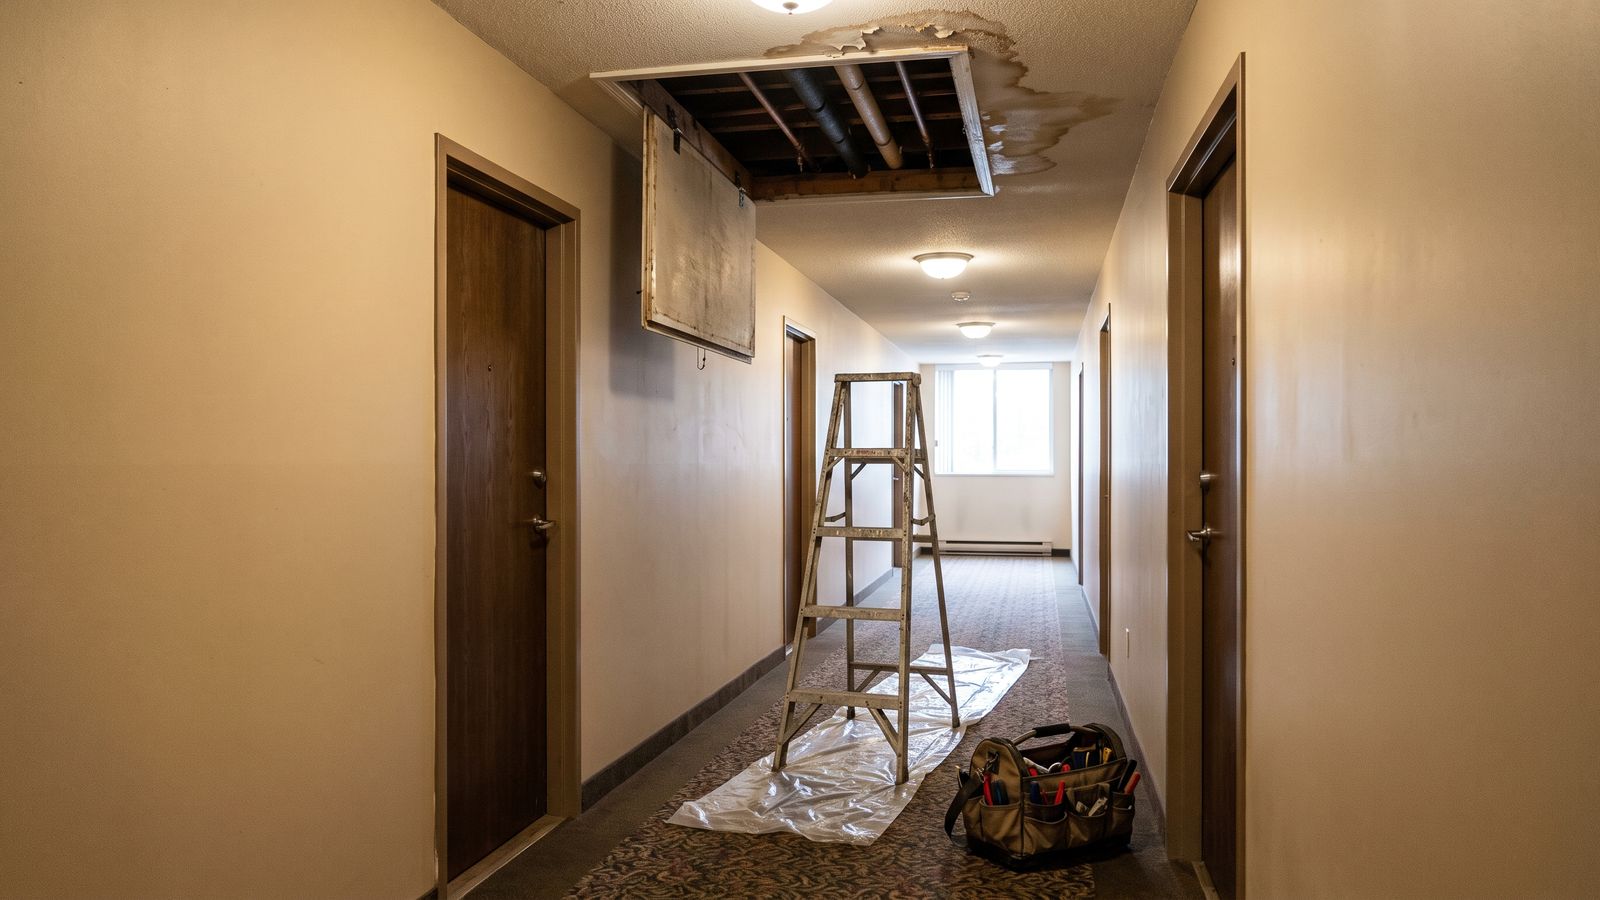
In stacked housing a blocked stack is a shared problem by design. A clog in a vertical waste line pushes flow out at the lowest fixture it can find, so a garden level can take damage from a blockage nobody on that floor caused. In newer mid-rises the blockage can be reached through a chase access panel in a common corridor, which puts the opening outside anyone's unit.
Water that backs up out of a sewer line is normally grossly contaminated, which puts it in Category 3 under the ANSI/IICRC S500 standard once the restorer inspects and makes the preliminary determination on site. That changes the work: carpet and pad come out rather than get dried in place, the wet band of drywall is removed, and the cavity is cleaned before any repairs. We pull a baseboard first and put the moisture meter on the bottom of the drywall, because the reading at the floor line is what sets how high the cut goes.
Questions about what your policy or the association's policy says about backup belong with your insurer or agent.
Who is responsible for the pipe inside the wall between two units?
The declaration decides, and the dividing line is usually how many units the pipe serves. A branch line serving your unit alone is typically maintained by the unit owner. A vertical stack or main serving more than one unit is typically a common element that the association maintains.
Between those two sits the limited common element: a component that serves a single unit but sits outside its boundary, such as a balcony or a dedicated shutoff in a corridor chase. Declarations handle those inconsistently, so read the paragraph twice.
The duty to repair the pipe and the duty to repair the water damage it caused are separate questions that may be answered in different parts of the document. Anything beyond that is a legal question for an attorney.
- Serves one unit only: usually the unit owner's pipe
- Serves two or more units: usually a common element the association maintains
- Serves one unit from outside its boundary: often a limited common element, and the declaration governs
- A shared wall does not automatically make the line inside it a common element
What do you do first when water comes from the unit above?
Stop the water, document it, and notify the people who need to know. Drying cannot wait for questions about responsibility to be settled. The mistake we see most often in condos is waiting: an owner is told the association will handle it, nothing dries for four or five days, and a wet drywall cavity turns into a mold question. Under the ANSI/IICRC S500 standard, clean water that sits and warms can degrade into a dirtier category, and the removal scope grows with it.
We document a stacked-housing loss with the boundary in mind: readings taken per unit, and photos and a scope that separate building materials from contents. We provide those records to you and, if your insurer or your association requests them, we provide them with your permission. We invoice the property owner.
Contact your own insurer or agent with questions about your policy. Coverage depends on your policy and your insurer's decision. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney.
- Shut off the source if you can reach it safely, and call the building's emergency line so staff can close the riser valve
- Cut power to the affected area if water is near outlets or the panel
- Photograph everything before anything moves, including the ceiling, the wet contents and the source
- Notify management in writing the same day
- Get a crew in to take moisture readings and start drying
- Keep receipts for anything you spend, and keep a sample of the removed material
- Sources: ANSI/IICRC S500, the water damage restoration standard
- S500 Consensus Body position statement on the category of water
- EPA's guidance on mold and moisture in the home