RCV vs ACV and Recoverable Depreciation on a Virginia Water Damage Claim
BY RESTORATION DOCTOR · NORTHERN VIRGINIA, MARYLAND & D.C.
Most homeowners policies pay a water loss in two parts: actual cash value now, with depreciation held back until the work is finished and proven. This guide covers how that deduction is calculated, what releases the holdback and by when, why the draft carries your mortgage servicer's name, and what to keep so the second check is not argued over.
Call 1-888-29-FLOODWhat is the difference between replacement cost and actual cash value?
On an RCV vs ACV water damage claim, the whole difference comes down to age. Replacement cost value, or RCV, is what it costs today to put the damaged part of your house back the way it was. Actual cash value, or ACV, is that same figure minus a deduction for the wear the materials already carried on the day of the loss. The first payment on most water losses is the ACV number, which is why it lands lower than the estimate you were shown.
Your declarations page decides which basis governs. A replacement cost policy is written to pay the full RCV in the end, but it pays in two parts: the ACV now, then the withheld depreciation later, once the repair is finished and proven. An actual cash value policy pays the depreciated number and closes there. Two houses on the same street can carry different bases, so never assume yours matches a neighbor's.
Read the estimate that arrives alongside the payment. It is a line-by-line document with a column for replacement cost, a column for depreciation, and a column for actual cash value. The summary page at the back is where the arithmetic is shown in full. That page, not the check stub, is the document to read first.
How is depreciation calculated on a water loss?
Depreciation is calculated line by line, not as one lump sum taken off the bottom. The adjuster's estimating software assigns each material an expected service life, then reduces its value according to how much of that life had already been used and what condition the material was in when the water reached it.
The inputs are judgment calls, and you are allowed to question them. Age, expected life, and pre-loss condition drive the deduction on every line. If the carpet in the finished basement was replaced two years ago, say so in writing and send the receipt. If the adjuster recorded the year the house was built as the age of the flooring, that is worth correcting before the estimate is finalized.
Watch which part of a line gets reduced. Some carriers depreciate only the material and leave the labor whole, while others reduce both. Emergency mitigation work, meaning the extraction and the drying days, is service already performed rather than property replaced, so it often carries little or no deduction. Your own estimate columns will show how your carrier handled each one.
| Estimate line | Why a deduction appears | What to check on your copy |
|---|---|---|
| Emergency mitigation: extraction, drying equipment, labor | Service already performed, nothing replaced | Whether the depreciation column reads zero on these lines |
| Drywall, insulation, paint | The materials had age and wear before the loss | Whether the deduction hits material only or material plus labor |
| Carpet and pad | Short expected service life, so this is often the largest deduction on the page | The age recorded for the flooring, and where that age came from |
| Baseboard, trim, interior doors | Wood and finish age like anything else | Whether finish work continues into rooms the water never reached |
| Cabinetry and vanities | Age plus the condition of the finish | Whether the line prices a repair or a full replacement |
| Contents and stored belongings | Often settled on a separate schedule with its own valuation | Whether contents are covered at replacement cost or actual cash value |
What makes depreciation recoverable, and what makes it not?
Depreciation is recoverable when your policy is written on a replacement cost basis and you actually complete the repair, then prove it. Until both of those are true, the withheld money stays with the carrier. Nothing about the holdback releases itself.
Some depreciation is non-recoverable by design. Certain policies apply it to specific categories, and roof coverage in particular is often written that way. Contents can settle on a different basis than the structure under the same policy. The estimate summary usually labels the two, so look for the word non-recoverable near the depreciation total and ask what falls under it.
Ask the question in writing and keep the answer. An adjuster saying on the phone that your depreciation is recoverable is worth much less than the same sentence in an email. The written answer is what you hold up months later, when a different adjuster has inherited the file.
- Is my policy replacement cost or actual cash value for the structure?
- Is the depreciation on this estimate recoverable, non-recoverable, or a mix?
- Which specific line items carry non-recoverable depreciation?
- What documents do you need from me to release the holdback?
- How long does my policy give me to complete the repair, and where is that paragraph?
- Is my mortgage servicer named on this payment, and if so, why?
Why is the first check short, and is that normal?
Yes, a short first check is normal, and on a replacement cost policy it is the system working the way it was designed. Three things come off the replacement cost total before that payment is cut: the depreciation holdback, your deductible, and sometimes an amount already advanced for the emergency work.
The arithmetic is easier to follow on the summary page than in a phone call. Start with the replacement cost total. Subtract the depreciation applied across the lines. Subtract your deductible once. What remains is the actual cash value payment, and that is the figure printed on the draft in your hand.
This catches people who expected one number and received another. About 83% of the projects we handle are billed through an insurance claim, so we sit with homeowners over this page most weeks of the year. A short check is not a denial, and on its own it is not a lowball offer either. It is a partial payment with the balance conditioned on finishing the work.
What do you have to do to get the holdback released?
To release the holdback you have to finish the repair and send the carrier proof that it was finished. In practice that means a final invoice from the contractor who did the work, evidence of what was paid or is owed, and dated photographs of the completed rooms.
Send it as one package with the claim number on every page. Carriers route supplements and depreciation releases through different queues, so label the email for exactly what it is: a request to release recoverable depreciation on a completed repair. Then ask for written confirmation that the package arrived and is complete.
Do not ask for the release before the work is genuinely done. Submitting a partly finished job as complete is the quickest way to lose standing on a file you may still need to supplement. If the repair is running in phases, ask the adjuster whether the carrier will release depreciation in stages as each phase closes out.
The same two-part mechanism runs in the other markets our sister offices serve, though the clocks around it differ by state. Our Florida team wrote up how the holdback works on a Florida claim at https://restorationdoctorfl.com/blog/acv-vs-rcv-first-insurance-check-florida, and the mechanic there is the same one described here.
- A final itemized invoice that matches the line structure of the carrier's estimate
- Proof of payment, or a statement showing the balance still due
- Dated photographs of each completed room, wide and close
- Any change orders, supplement approvals, or scope revisions
- The claim number written on every page of the package
- A short cover note stating the repair is complete and requesting the depreciation release
Is there a deadline, and what happens if you miss it?
Most replacement cost policies set a window for completing the repair and claiming the holdback, and that window is set by your own policy language. Some are measured from the date of loss and some from the date of the first payment. Read yours, and if the wording is unclear, ask the carrier to point you to the paragraph.
If the repair will run past the window, ask in writing for an extension before the date passes rather than after. Carriers will often grant extensions for reasonable causes such as permit delays, long lead times on materials, or a house that cannot be occupied. The request is far easier to approve while the deadline is still ahead of you.
Miss the window with no extension and the practical result is that you keep the actual cash value and lose the rest. If you believe a holdback was refused unfairly, Virginia's insurance regulator, the Bureau of Insurance at the State Corporation Commission, accepts consumer complaints about how a claim was handled. That is worth knowing about even if you never need to use it.
Why does the check have your mortgage company's name on it?
Your check carries the mortgage company's name because the lender is listed on your policy as mortgagee or loss payee and holds an interest in the house securing its loan. Naming the servicer on the draft is routine, not a signal that something is wrong with your claim.
Loss draft departments commonly require an inspection before they release a large draft, so a homeowner in Fairfax or Loudoun is usually running two clocks at once. One is the carrier's window for completing the repair. The other is the servicer's disbursement schedule, which may hand the money back in stages instead of all at once.
Smaller payments sometimes arrive without the servicer's name and larger ones usually do not. The threshold varies, and it is set in your loan documents rather than by the carrier. When a draft shows up with two names on it, your next call is to the servicer, not to the adjuster.
How do you get a mortgagee to endorse and release the funds?
Call your mortgage servicer, ask for the loss draft department, and ask that department for its written process. Most of them have one in writing. The forms, the signatures, and the inspection triggers differ enough between companies that guessing at them costs weeks.
In general terms, the servicer will want the draft itself, the carrier's estimate, and a contract or invoice from the contractor doing the repair. It may hold the money in a restricted account and release it in stages as inspections confirm progress. Ask the servicer precisely how the draft should be handled and who has to sign what, because a paperwork error sends the file back to the start of the queue.
Keep a record of every call: the date, the name of the person you spoke to, and what was agreed. Ask what triggers each disbursement and how long an inspection takes to schedule. If the servicer's release schedule and the carrier's repair deadline do not line up, tell the adjuster in writing early rather than explaining it afterward.
- The servicer's written loss draft procedure, in a document you can keep
- Which forms it needs, and who must sign each one
- Whether funds come in one payment or in staged disbursements
- What triggers each inspection, and how quickly one can be booked
- Where the funds are held while the repair is underway
- Who to contact at the servicer when a disbursement stalls
What if the actual repair costs more than the estimate?
When the repair costs more than the approved estimate, the route is a supplement rather than a fight. A supplement is a request to revise the approved scope because something turned up that the first estimate could not have accounted for.
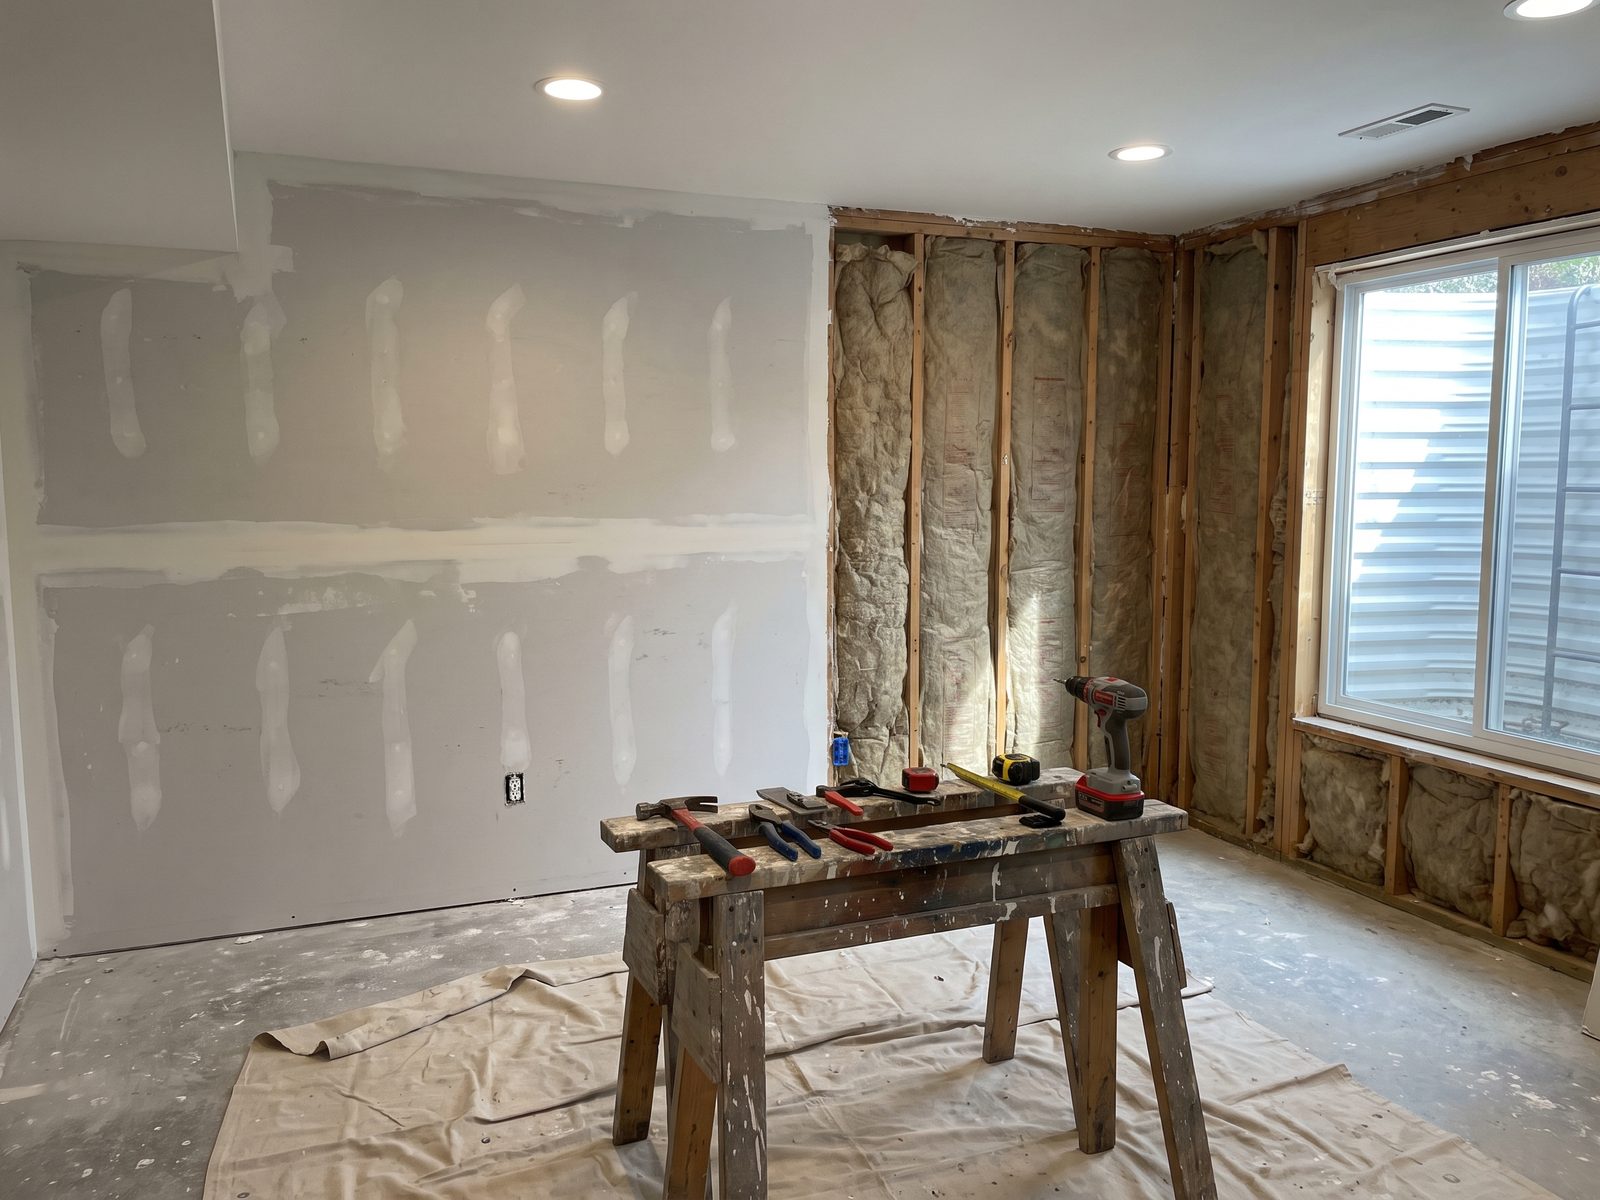
Hidden damage is the usual cause on a water loss. We pull the baseboard first, and the moisture meter often reads wet a foot or two past where the staining stops. Insulation inside an exterior wall holds water long after the drywall face feels dry to the hand. None of that is visible on the morning the adjuster walks the house with a clipboard.
Document it before it disappears behind new drywall. Dated photographs, meter readings, and a written explanation of what changed carry a supplement much further than a revised total on its own. Send it while the wall cavity is still open. A supplement filed after the room is finished becomes an argument, while one filed with the cavity photographed is simply a record.
What should you keep as proof of completion?
Keep a paid final invoice itemized in the same shape as the carrier's estimate, together with photographs and the drying records from the mitigation phase. That set is what turns the holdback into a second payment without a round of questions.
Mitigation documentation matters more than homeowners expect. Daily moisture readings, equipment counts, and psychrometric logs recorded under the ANSI/IICRC S500 standard show that the structure actually reached a dry standard before anything was closed up. Where mold came into it, EPA cleanup guidance and the ANSI/IICRC S520 standard are the references an adjuster recognizes on sight.
Restoration Doctor works across Northern Virginia from our Vienna headquarters, and our crews document a job as it runs instead of reconstructing it afterward. Keep your own copies as well. Claim files move between adjusters, and the homeowner who kept the folder gets the second check without relitigating the first.
- The final itemized invoice, priced line by line against the approved scope
- Proof that the invoice was paid, or a statement of the balance owed
- Before, during, and after photographs with dates attached
- Daily moisture and psychrometric logs from the drying phase
- Permits, inspection sign-offs, and any material or product receipts
- Sources:
- ANSI/IICRC standards overview, https://iicrc.org/iicrcstandards/
- EPA guidance on mold cleanup in your home, https://www.epa.gov/mold/mold-cleanup-your-home
- Virginia SCC Bureau of Insurance, how to file an insurance complaint, https://scc.virginia.gov/consumers/insurance/file-an-insurance-complaint/